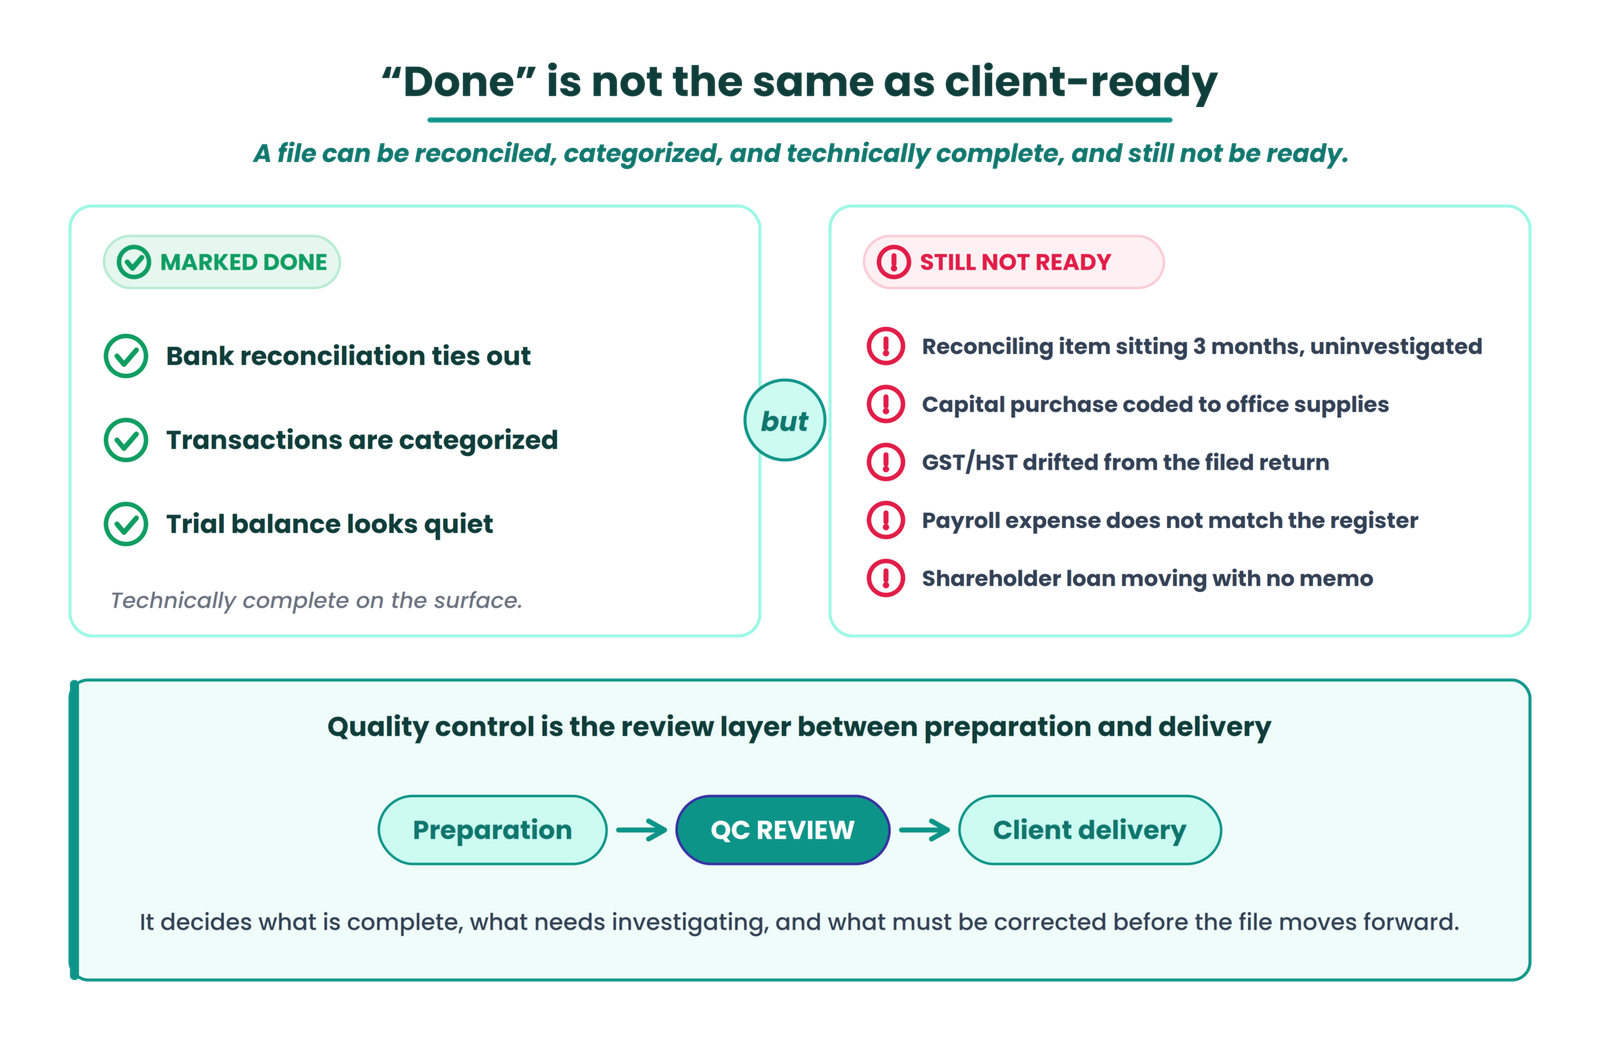
A bookkeeping file can be reconciled, categorized, and technically complete without being ready for client delivery. The bank reconciliation ties out. Transactions have categories. The trial balance isn’t screaming.
And the file still isn’t ready.
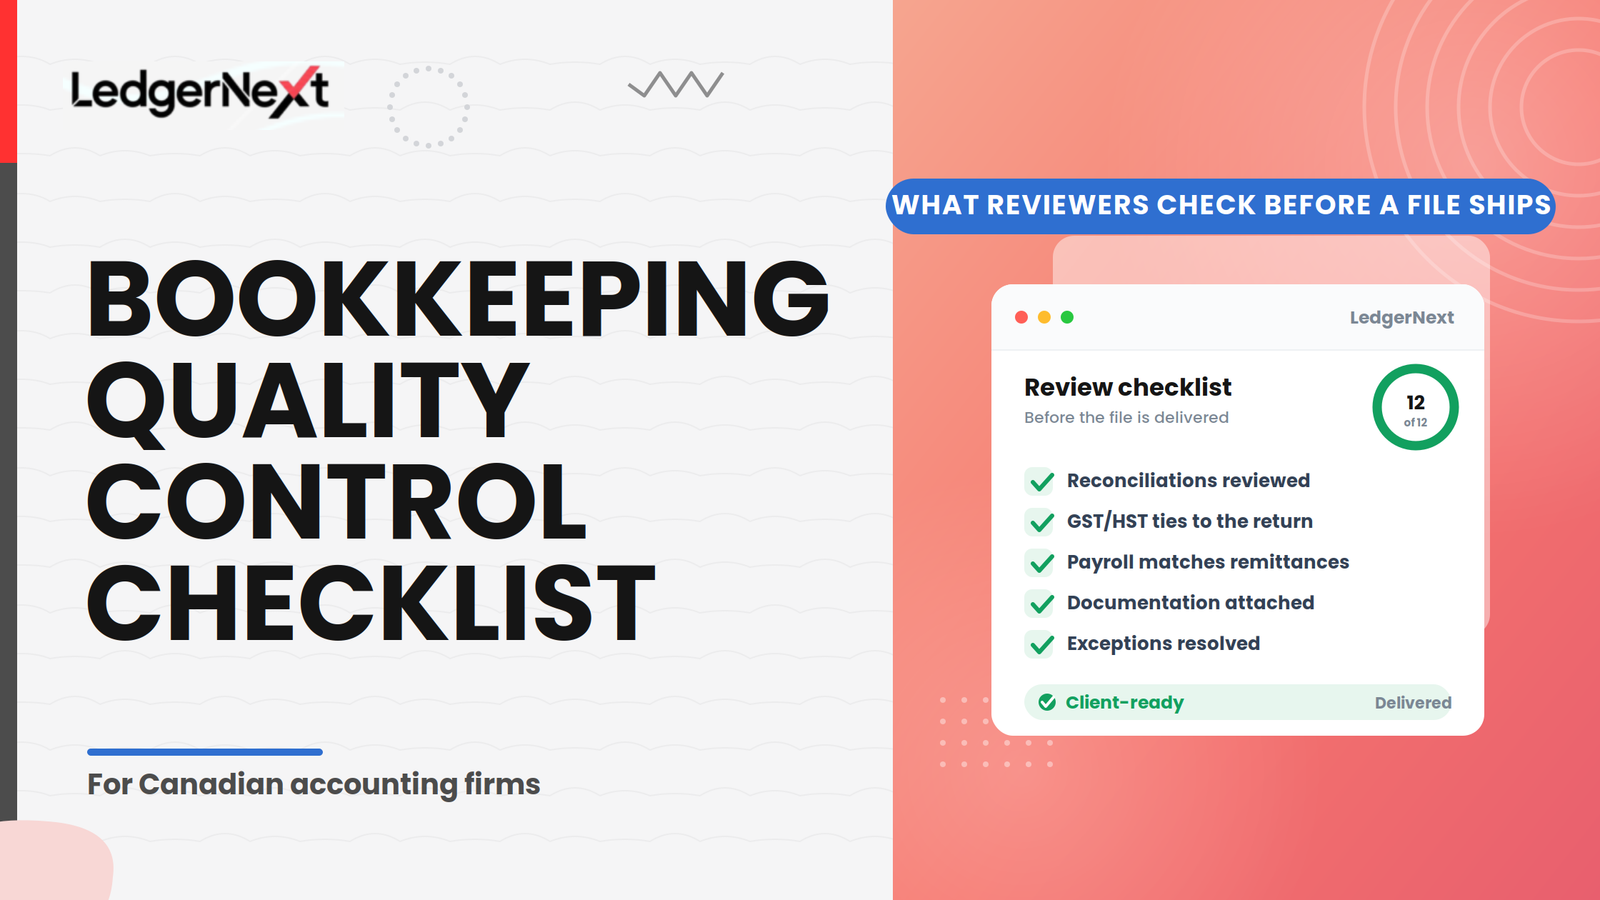
Maybe an old outstanding item has been sitting on the reconciliation for three months and nobody’s investigated it. A large expense got coded to office supplies when it’s clearly a capital purchase. The GST/HST liability account drifted from the filed return two quarters ago and nobody traced why. Payroll expense in the ledger doesn’t match the payroll register. A shareholder loan balance keeps moving with no memo attached to any of the entries.
These aren’t rare edge cases. They’re what bookkeeping reviewers find constantly when a file gets marked “done” without a structured review layer between preparation and delivery.
A bookkeeping quality control process gives the reviewer a consistent way to determine what is complete, what needs investigation, and what must be corrected before the file moves forward. By the end of this guide, you’ll have a framework your firm can adapt to review bookkeeping work across clients and team members, including how to handle exceptions when they surface.
In short
Bookkeeping quality control is the structured review of a client’s bookkeeping records to verify completeness, consistency, supporting documentation, reconciliations, unusual transactions, and unresolved exceptions before the file is finalized or delivered.
Bookkeeping quality control checklist at a glance
Who this applies to (and who it doesn’t)
This framework is built for Canadian accounting firms, bookkeeping firms, and CPA practices that manage bookkeeping work across multiple clients with a team that includes preparers and reviewers. If your firm is scaling from owner-does-everything to delegated bookkeeping with a review layer, this is where to start formalizing that layer.
If you’re a business owner doing your own books, this isn’t your article. If you’re looking for a month-end close procedure, we have a month-end close checklist for Canadian accounting firms that covers that workflow specifically.
The 7-step bookkeeping QC workflow
This isn’t an official Canadian accounting standard. It’s a practical workflow that accounting firms can adapt to their own review procedures and engagement requirements.
→
Check completeness
→
Review
→
Identify exceptions
→
Correct
→
Re-review
→
Sign off
| Stage | Reviewer objective | Typical checks | Output |
|---|---|---|---|
| 1. Prepare | Confirm the file is ready for review | Completeness, outstanding requests, period confirmed | Review-ready status |
| 2. Check completeness | Verify all expected information is present | Bank statements, credit cards, source documents, new accounts | Go/no-go for review |
| 3. Review | Evaluate the bookkeeping work | Reconciliations, transactions, balances, documentation, tax entries | Review notes |
| 4. Identify exceptions | Flag items requiring investigation or correction | Unexplained balances, missing support, coding issues, variances | Exception log |
| 5. Correct | Preparer addresses flagged items | Reclassifications, missing entries, documentation | Updated file |
| 6. Re-review | Confirm corrections resolve the exceptions | Targeted re-check of flagged items | Updated exception log |
| 7. Sign off | Authorize the file for delivery | Final status confirmed | Client-ready file |
The second time a firm runs this workflow, it usually narrows the checklist to the highest-risk accounts and stages. That’s expected. The first pass is about building the muscle; every pass after that gets faster because reviewers know what to look for and preparers learn what gets flagged.
What the reviewer actually checks
File completeness
Before reviewing whether the numbers are right, confirm that the reviewer actually has the information needed to assess the file. A missing bank statement or unresolved client request can make an otherwise polished file impossible to review properly.
Check expected bank accounts, credit-card accounts, statements, source documents, client information, new accounts opened during the period, missing periods, and outstanding client requests.
The reviewer question here is simple: do I have enough information to meaningfully review this file? If the answer is no, the file goes back before any review work begins.
Reconciliation review
“Reconciled” is a status, not the end of the review.
Canadian practice-oriented checklists emphasize that all bank and credit card accounts should be reconciled to the statement and that no unmatched items older than 30 days should remain in a clean file. But a reconciliation that technically ties can still contain miscategorized items, duplicate postings, stale credits, or deposits that were forced to match but never explained.
The reviewer checks the statement ending balance, reconciliation status, outstanding items (especially old ones), duplicate transactions, unexplained differences, missing accounts, and unusual adjustments. If any reconciling item is older than 30 days, stop and investigate the clearing path before moving on.
For firms that keep running into reconciliation issues that survive the matching process, our coverage of problems that persist after reconciliation goes deeper into diagnosis.
Transaction review
The purpose of QC is not to inspect every transaction equally. Review effort should be concentrated on transactions and accounts with a higher likelihood of error or material impact.
A reviewer focuses on uncategorized transactions, suspense or miscellaneous account balances, large or unusual transactions, new vendors, new categories, personal and business items where applicable, capital versus operating expenditure decisions, and inconsistent recurring transactions. A practical stop/go test: pick five random transactions. If two or more lack support, stop and clean the source documentation layer first.
That risk-based approach matters. A firm with 40 clients can’t have reviewers manually scanning every line. They need to know where errors cluster. If you’re working on reducing bookkeeping errors without slowing your team down, that’s a related but distinct problem from the review process itself.
Supporting documentation
The reviewer should be able to move from financial statement to account to transaction to supporting evidence where appropriate. Invoices, receipts, contracts where relevant, payment evidence, supporting schedules, and documentation for adjustments all fall into scope.
Many checklists ignore documentation quality entirely. The transaction may be booked, but the support is missing, unclear, or not retrievable. That gap becomes a real problem at compilation time. Canadian compilation prep checklists require year-end bank statements, credit card statements, trial balance exports, A/R and A/P listings, loan statements, payroll records, and asset lists as standard inputs.
GST/HST-related bookkeeping
What should a bookkeeping reviewer check before accepting the GST/HST-related bookkeeping? Tax coding consistency, GST/HST liability and receivable account balances, unusual tax treatment on specific transactions, supporting documentation for input tax credits, filing-period consistency, significant adjustments, and unexplained tax balances.
CRA requires that businesses maintain adequate records to support ITC claims, and those records need to be available for review. If the GST/HST return doesn’t tie to the books, the root cause is usually timing differences or misclassified tax codes. Compare filed return totals to tax liability accounts line by line before filing.
Payroll-to-books review
Payroll may be processed correctly while the accounting records are still incomplete or incorrectly posted. That’s the bookkeeping-review angle.
The reviewer compares payroll records to accounting entries, checks payroll expenses, payroll liabilities, remittance-related balances, adjustments, and unusual payroll entries. Payroll totals have to match remittances and T4 summaries. A common ghost error: vacation accruals, bonuses, or manual journals create a gap between payroll remittances and payroll expense in the ledger that nobody traces until year-end.
Balance-sheet review
This is where the framework Balance, Evidence, Explanation, Action earns its keep.
For every significant balance-sheet account (bank, credit cards, AR, AP, loans, GST/HST, payroll liabilities, fixed assets, prepaid expenses, owner/shareholder-related balances), the reviewer asks: can I explain why this balance exists, and what supports it?
Owner and shareholder loan balances deserve extra attention. They’re often treated as a catch-all account until year-end, which creates tax and disclosure risk. CRA and CPA guidance both flag related-party balances as areas requiring clear documentation. If any transfer on a shareholder loan lacks a memo or business purpose, stop and classify it properly.
P&L review
Don’t just check arithmetic. Look at month-over-month changes, prior-period comparison, unusual expense movements, revenue changes, new accounts, missing recurring expenses, unexpected margins, and negative balances.
The question is: what changed, why did it change, and does the explanation make sense? A trial balance that looks stable and plausibly aligned with prior periods, without unexplained jumps, is a good signal. Large movements with no explanation are a red flag.
Journal entries and adjustments
Firms should define their own approval and documentation controls based on their engagement and risk requirements. The reviewer checks the reason, date, accounts affected, amount, supporting documentation, reviewer notes, approval per firm policy, and the resulting balance.
How exceptions get handled
Every exception needs an owner, an action, and a status. Without that, review notes become a graveyard of observations nobody acts on.
| Field | Purpose |
|---|---|
| Client | Identify file |
| Account | Locate issue |
| Issue | Describe exception |
| Owner | Assign responsibility |
| Status | Track progress (Open, Waiting on client, In progress, Corrected, Re-review required, Closed) |
| Action | State what must happen |
| Resolution | Document outcome |
| Reviewer | Confirm closure |
This is where much of the effort goes in practice. Firms spend significant time on evidence collection, reviewer sign-off, issue tracking, and standardizing exceptions across clients. The exception log is what turns a checklist into a workflow.
Completed, review-ready, and client-ready are three different things
| Status | Meaning | Who owns it | What happens next |
|---|---|---|---|
| Completed | Preparer has finished assigned bookkeeping work | Bookkeeper | Self-check, then submit for review |
| Review-ready | Required preparation and self-checks are complete; reviewer has information needed | Bookkeeper/reviewer | Reviewer begins QC |
| Client-ready | Review exceptions are resolved or documented; file has passed the firm’s delivery controls | Reviewer | File delivered to client |
Treating these as interchangeable is how files get sent out with unresolved items still sitting in them.
Where practitioners disagree
There’s a live disagreement about how much documentation a bookkeeping QC review itself needs. Some firm owners argue that the reviewer’s sign-off is sufficient, that over-documenting the review process creates busywork that slows delivery. Others, especially those preparing files for compilation engagements where Canadian Standards on Quality Management apply, argue that the review trail is the evidence that QC happened. CPA Ontario’s guidance on CSQM confirms that quality management obligations extend to compilation engagements. I land on the side of documenting, because an undocumented review is indistinguishable from no review at all when someone else picks up the file six months later.
Ghost errors that survive a “clean” file
| Symptom | Root cause | The fix |
|---|---|---|
| Bank rec ties but cash still looks off | Prior-period edits or uncleared duplicates | Rebuild the reconciliation from the statement date forward and inspect opening balance changes |
| GST/HST return doesn’t tie to books | Timing differences or misclassified tax codes | Compare filed return totals to tax liability accounts line by line |
| Payroll remittances don’t match payroll expense | Vacation accruals, bonuses, or manual journals | Reconcile payroll register to remittance summaries and separate accrual entries |
| Owner loan balance keeps changing | Personal/firm mixed expenses and undocumented transfers | Force a memo for every related-party movement and review monthly |
| A/R aging shows old balances that “should be fine” | Invoices marked paid without real deposits | Match deposits to invoices, not just invoice status flags |
| Trial balance has one odd account everyone ignores | Mapping issue or suspense account leakage | Review all suspense/clearing accounts monthly and require zero-balance sign-off |
Scaling QC across multiple clients
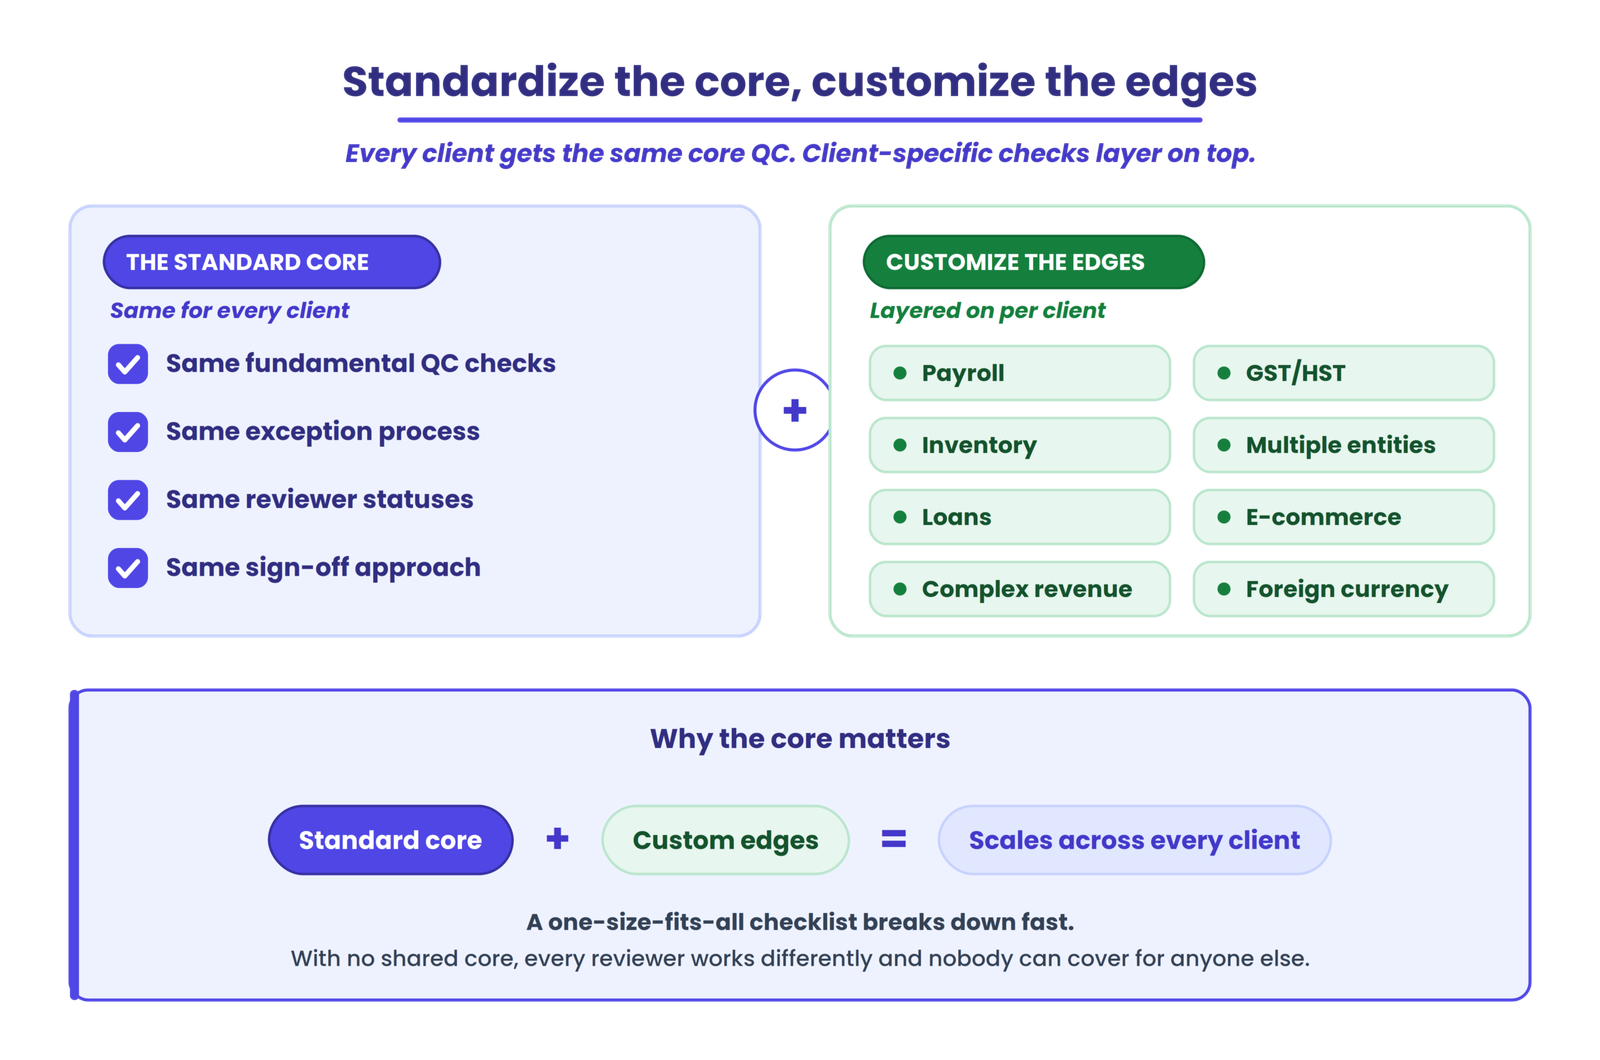
Standardize the core: every client gets the same fundamental QC checks, the same exception process, the same reviewer statuses, the same sign-off approach. Customize the edges: client-specific checks for payroll, GST/HST, inventory, multiple entities, loans, e-commerce, complex revenue, or foreign currency get layered on top.
A one-size-fits-all checklist breaks down fast. But a firm with no standard core ends up with every reviewer doing something different for every client, and nobody can cover for anyone else.
For firms working on building standardized workflows across every client, the QC layer is where standardization pays off most visibly.
How technology supports bookkeeping QC
Automated matching, transaction rules, exception identification, centralized client data, standardized workflows, reviewer visibility, centralized review notes, document collection, client communication, multi-client dashboards, and review trails all reduce the manual overhead of QC.
Once firms move from a handful of clients to a larger multi-client operation, maintaining consistent review procedures becomes increasingly dependent on centralized visibility and standardized workflows. LedgerNext is built around that problem: multi-client bookkeeping with centralized categorization, reconciliation, and review visibility so that fewer things fall between the cracks during handoff from preparer to reviewer.
Automation should reduce repetitive review work and surface exceptions. It should not replace professional judgment.
Give every bookkeeping review the same structured checklist
Firms running QC across a growing client book can see how centralized bookkeeping workflows keep categorization, reconciliation, and review visibility consistent from preparer to reviewer.
Frequently asked questions
What is bookkeeping quality control?
Bookkeeping quality control is the structured review of a client’s bookkeeping records to verify completeness, consistency, supporting documentation, reconciliations, unusual transactions, and unresolved exceptions before the file is finalized or delivered. It sits between bookkeeping preparation and client delivery as a distinct control layer.
What should a bookkeeping reviewer check?
A bookkeeping reviewer should verify file completeness, then review reconciliations, transaction categorization, supporting documentation, GST/HST-related bookkeeping, payroll-related entries, significant balance-sheet accounts, P&L movements, manual journal entries, and unresolved exceptions.
What makes a bookkeeping file review-ready?
A file is review-ready when the preparer has finished assigned work, completed self-checks, and provided the reviewer with all information needed to assess the file. That includes statements, source documents, and responses to outstanding questions. Completed and review-ready are different statuses.
How often should bookkeeping quality control be performed?
At minimum, before any client delivery point: monthly close, quarterly reporting, GST/HST filing periods, and year-end. Firms handling compilation-ready files typically perform QC at every reporting period.
Should every transaction be manually reviewed?
No. Review effort should be concentrated on transactions and accounts with a higher likelihood of error or material impact. Risk-based review means the reviewer focuses on uncategorized items, large transactions, new vendors, unusual entries, and accounts that have historically produced exceptions.
How can accounting firms standardize bookkeeping reviews across clients?
By maintaining a core QC checklist that applies to every client, a standard exception process with consistent statuses, and a standard sign-off approach. Client-specific review items get layered on top of that core rather than replacing it.
What comes next
Good QC isn’t about checking everything manually. It’s about creating a repeatable review system that identifies what needs attention, assigns exceptions, confirms corrections, and gives the firm confidence that the file is ready for the next stage.
The first cycle through this framework will feel slow. Expect that. The second cycle will be faster because your preparers will learn what gets flagged, your reviewers will know where to look, and your exception log will start showing patterns instead of surprises.
The next problem most firms hit after formalizing QC is tracking exception volume across clients to figure out where the preparation process itself needs to change. That’s a capacity and workflow question, and it’s worth solving separately.
Standardize QC across every client from one place
LedgerNext centralizes multi-client bookkeeping so categorization, reconciliation, and review visibility stay consistent, and fewer things fall between the cracks during the handoff from preparer to reviewer.